Retirement changes your financial situation. Employment income may decrease or disappear, while AHV, occupational pension benefits, private retirement savings and personal assets become the financial foundation.
At the same time, your spending can change. Work-related expenses may disappear, while leisure, travel, healthcare and other personal needs may become more important.
There is therefore no single amount that guarantees a good retirement. The important question is what kind of lifestyle you want and what it will cost.
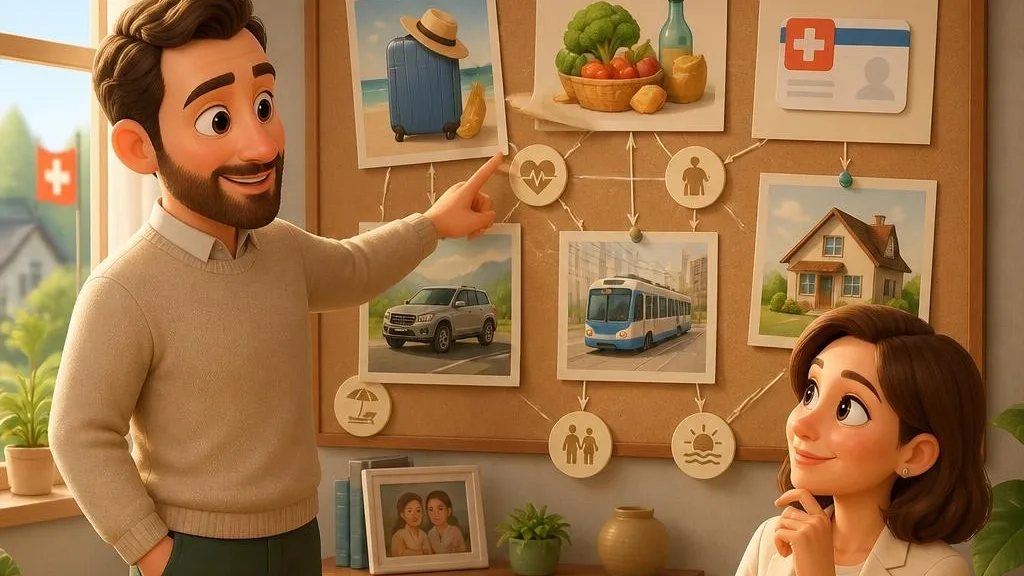
What Costs Should You Expect in Retirement?
A realistic budget should include all major areas of spending.
Housing
Housing is one of the largest regular expenses for many households. This can include:
- rent or mortgage interest
- additional housing costs
- electricity and energy
- maintenance and repairs
- insurance
- other property-related expenses
Homeowners should also plan for major repairs and renovations over the long term.
Health Insurance and Healthcare
Healthcare expenses can become increasingly important with age. In addition to health insurance premiums, your budget may need to include deductibles, co-payments, medication, dental treatment and other healthcare expenses.
A long-term retirement plan should therefore allow for additional healthcare costs.
Food and Household Expenses
Food, clothing, household products and personal expenses remain part of the budget after retirement.
The amount depends heavily on your lifestyle and whether you live alone or as a couple.
Leisure and Travel
Retirement often provides more free time. Travel, restaurants, sports, cultural activities and hobbies can therefore represent a larger part of your budget.
If you want to travel regularly or pursue more expensive hobbies, these expenses should be included in your retirement planning.
Mobility
Mobility costs may also change. Commuting may no longer be necessary, but you may still have expenses for a car, public transport or travel.
If you own a car, also consider insurance, taxes, servicing, repairs and future replacement costs.
How Much Should Your Retirement Budget Be?
Average figures can provide an initial reference, but your own budget is what matters for personal planning.
Consider factors such as:
- housing costs
- health insurance and healthcare
- food
- mobility
- leisure and travel
- insurance
- taxes
- provisions for major expenses
- financial support for children or relatives
A couple who own their home outright, for example, will have a different financial situation from a single person renting an apartment.
Regular and Irregular Expenses
Retirement planning should not focus only on monthly fixed expenses.
Additional costs may arise from:
- renovations
- major repairs
- dental treatment
- replacing a car
- household appliances
- major holidays
- supporting family members
A financial reserve can provide flexibility when these expenses occur.
What Income Will You Have in Retirement?
Your expected expenses should be compared with your expected income.
Potential sources include:
- AHV pension
- occupational pension benefits
- Pillar 3a savings
- investment income
- rental income
- part-time employment income
The key figure is the difference between your expected income and your desired spending.
Example: How a Funding Gap Can Arise
Suppose a couple wants a retirement budget of CHF 7,000 per month.
Their expected income from AHV and occupational pensions totals CHF 5,500 per month.
This creates a difference of:
CHF 1,500 per month or CHF 18,000 per year.
The gap could be financed through personal assets, investment returns, private retirement savings or additional income.
This example shows why retirement planning is not only about the size of your pension. It is about whether your total income matches the lifestyle you want.
How Much Wealth Do I Need?
If regular pension income is not sufficient, personal assets can help cover the funding gap.
However, you should not simply divide your assets by the number of years you expect to be retired. Investment returns, inflation, taxes and unexpected expenses can all affect the outcome.
Long-term financial planning should therefore consider different scenarios.
Your Expenses May Change Over Time
Your financial needs do not necessarily remain the same throughout retirement.
During the first years, many people spend more on travel, leisure and activities. Later, healthcare and support services may become more important.
A good retirement plan should therefore consider the entire expected retirement period rather than focusing only on the first few years.
Consider Inflation
Price increases can also affect your retirement finances. The same lifestyle may cost more in the future if living costs increase.
Long-term planning should therefore not rely exclusively on today’s expenses.
Over a long retirement period, inflation can have a significant effect on the purchasing power of your assets.
What Does a Good Retirement Mean?
A good retirement looks different for everyone.
For some people, it means travelling frequently. Others value a comfortable home, time with family, hobbies or financial security.
Retirement planning should therefore not begin with the question of how little you can spend. A better starting point is to define the lifestyle you want and then create a realistic budget around it.
Conclusion
There is no universal amount that defines a good retirement.
Your costs depend on housing, healthcare, leisure, mobility, taxes and your personal circumstances. At the same time, AHV, occupational pensions, private retirement savings and personal assets should all be considered.
By comparing expected income and expenses early, you can identify potential funding gaps and adjust your financial planning accordingly.
FAQs
It depends on your desired lifestyle and personal circumstances. The key factor is the difference between your expected income and expenses.
In addition to housing, health insurance, food and mobility, consider leisure, travel, taxes and provisions for larger or unexpected expenses.
AHV is an important part of retirement income. Whether it is sufficient together with other income depends on your individual financial needs.
Compare your expected monthly income with your estimated expenses. The difference indicates how much additional funding may be required.
Yes. Over a long retirement period, inflation can affect future living costs and the purchasing power of your assets.