What Is an Emergency Fund?
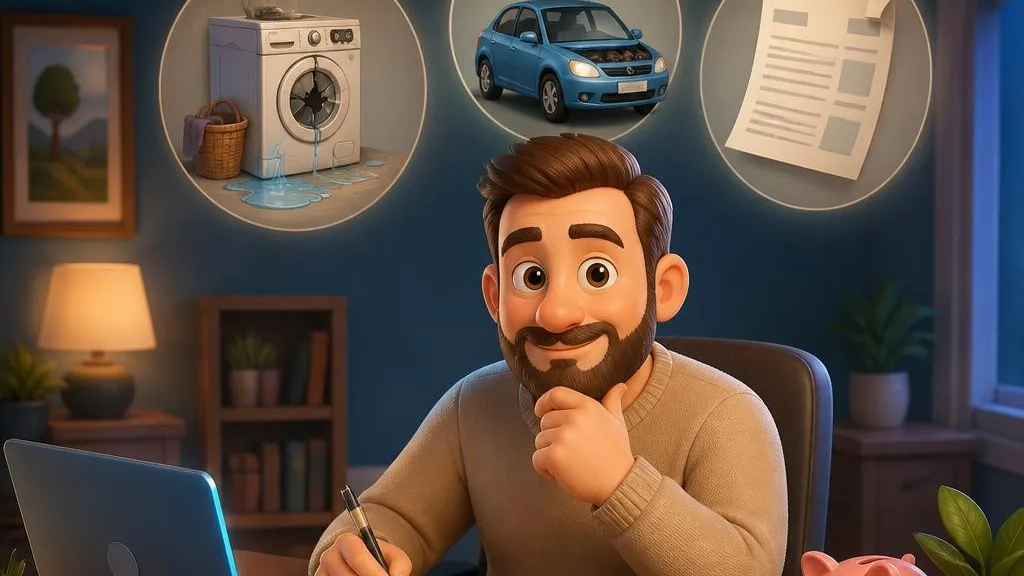
An emergency fund is money set aside for unexpected financial expenses. This could include an urgent car repair, a broken household appliance, unexpected healthcare costs or another significant expense.
Unlike long-term investments, an emergency fund should be readily accessible. Its main purpose is therefore financial security rather than maximizing returns.
A liquid reserve is an important part of financial planning because unexpected expenses can arise at any time.
Why Is an Emergency Fund Important?
Unexpected expenses cannot always be avoided. Without an emergency fund, a large bill may force you to borrow money, use a credit card or sell long-term investments at an inconvenient time.
An emergency fund provides a financial buffer.
It can help you:
- pay unexpected bills
- cover temporary income interruptions
- avoid selling investments at the wrong time
- reduce the need for short-term debt
- make financial decisions with greater confidence
A reserve is therefore not simply money sitting unused in an account. It is part of a sound financial plan.
How Much Should an Emergency Fund Be?
A commonly used rule of thumb is to keep around three months of income as an emergency reserve. UBS, for example, refers to three monthly salaries as a possible initial benchmark.
However, this is not a universal requirement.
The appropriate amount depends on factors such as:
- monthly fixed expenses
- income and job security
- number of people in the household
- home ownership or renting
- car and other financial commitments
- self-employment
- existing insurance coverage
- family responsibilities
- existing assets
People with higher fixed costs or less predictable income may need a larger reserve.
Monthly Income or Monthly Expenses?
For personal planning, it can be more useful to look at essential monthly expenses rather than income alone.
Start by calculating how much you need each month for essential costs such as:
- housing
- health insurance
- food
- transportation
- insurance
- taxes
- other fixed commitments
You can then decide how many months of essential expenses your reserve should cover.
Example
Suppose your essential monthly expenses amount to CHF 4,000.
A reserve covering three months of expenses would therefore be:
CHF 4,000 × 3 = CHF 12,000
Whether CHF 12,000 is enough depends on your individual circumstances.
Who May Need a Larger Reserve?
Different households face different levels of financial risk.
Self-employed people
Self-employed people may experience greater income fluctuations than employees. A larger cash reserve can therefore be useful.
Families
Unexpected expenses can have a larger impact on family budgets. Repairs, healthcare costs and expenses related to children can quickly add up.
Homeowners
Homeowners should consider potential maintenance and repair costs in addition to their general emergency fund.
A broken heating system or major household repair can easily cost several thousand francs.
People with Variable Income
People whose income depends heavily on bonuses, commissions or project-based work may also benefit from a larger reserve.
What Should an Emergency Fund Cover?
An emergency fund is intended for unexpected or urgent expenses.
These may include:
- urgent repairs
- unexpected medical costs
- replacement of essential household appliances
- unexpected transportation expenses
- unforeseen bills
- temporary income interruptions
It normally should not be used for planned expenses such as holidays, a new car or a planned renovation.
Those goals should have separate savings arrangements.
An Emergency Fund Is Not the Same as a Savings Goal
It is important to distinguish between an emergency fund and goal-based savings.
An emergency fund is for situations you could not reasonably plan for.
A holiday budget, a car purchase or a planned renovation are foreseeable expenses.
Keeping these categories separate can prevent you from using your emergency reserve for normal spending.
A simple structure could be:
Emergency fund → unexpected expenses
Savings goals → planned expenses
Investments → long-term wealth building
Where Should You Keep Your Emergency Fund?
An emergency fund should generally be liquid and easily accessible.
A savings account can be suitable for this purpose. However, Swiss savings accounts may have withdrawal restrictions or notice periods, so the specific conditions should always be checked.
The interest rate is therefore not the only consideration. Accessibility and security are also important.
Should You Invest Your Emergency Fund?
Money that may be needed in the short term should generally not be exposed unnecessarily to significant market fluctuations.
Stocks and other investments can offer attractive long-term return potential, but their value can fluctuate considerably in the short term.
If you need to sell an investment at an unfavourable time, you may have to accept a loss.
An emergency fund therefore serves a different purpose from a long-term investment portfolio.
How Do You Build an Emergency Fund?
If you do not have a reserve yet, you do not necessarily need to save several thousand francs immediately.
Building it gradually can be more realistic.
For example:
- Set a personal target
- Determine a monthly savings amount
- Transfer the money regularly to a separate account
- Build the reserve until you reach your target
- Review the amount regularly
Even smaller monthly amounts can add up over time.
If you save CHF 500 per month, for example, you would have accumulated CHF 6,000 after one year, assuming you do not need to use the money.
What If You Need to Use Your Emergency Fund?
An emergency fund is not designed to remain untouched forever.
If an unexpected expense occurs, using the reserve means it is doing exactly what it was designed to do.
Afterwards, however, you should consider rebuilding the amount.
For example, if you have CHF 15,000 in your emergency fund and need CHF 5,000 for an urgent repair, your reserve falls to CHF 10,000.
Your next financial priority may therefore be to rebuild the missing amount.
Can You Have Too Much Cash?
An excessively large cash reserve can also be inefficient.
Money that is unlikely to be needed for many years may, depending on your personal situation, be better suited to long-term financial goals or investments.
The important question is not simply how much money you can keep in your account, but how much you actually need to have readily available.
The better question is:
“How much money needs to be immediately available so that I can handle unexpected expenses without disrupting my long-term financial plan?”
Conclusion
An emergency fund is an important part of sound financial planning. It provides protection against unexpected expenses and can reduce the need to sell long-term investments or take on debt.
As a general starting point, around three months of income or several months of essential expenses can be considered. The appropriate amount, however, depends on your personal circumstances.
The key is to keep your emergency fund separate from planned savings goals and long-term investments.
FAQs
A common rule of thumb is around three months of income. The appropriate amount depends on your expenses, income stability and personal commitments.
It should be safe and readily accessible. A suitable savings account can be an option, although withdrawal conditions should be checked.
Money that may be needed at short notice should generally not be exposed unnecessarily to market fluctuations. Long-term investments serve a different purpose.
An emergency fund covers unexpected expenses. A savings goal is intended for planned expenses such as holidays, a car or a renovation.
They may, particularly if their income fluctuates or is less predictable. The appropriate amount should be based on their individual financial situation.